Sacred Yew Mortgages logoπŸ’¬ Chat

Right to Buy Guide

Thinking About Buying Your Council Home?

If you are an eligible council tenant, Right to Buy might allow you to purchase your home at a discount from its market value.

Before arranging a mortgage, it is important to understand your eligibility, discount, property value, monthly affordability and the costs involved in becoming a homeowner.

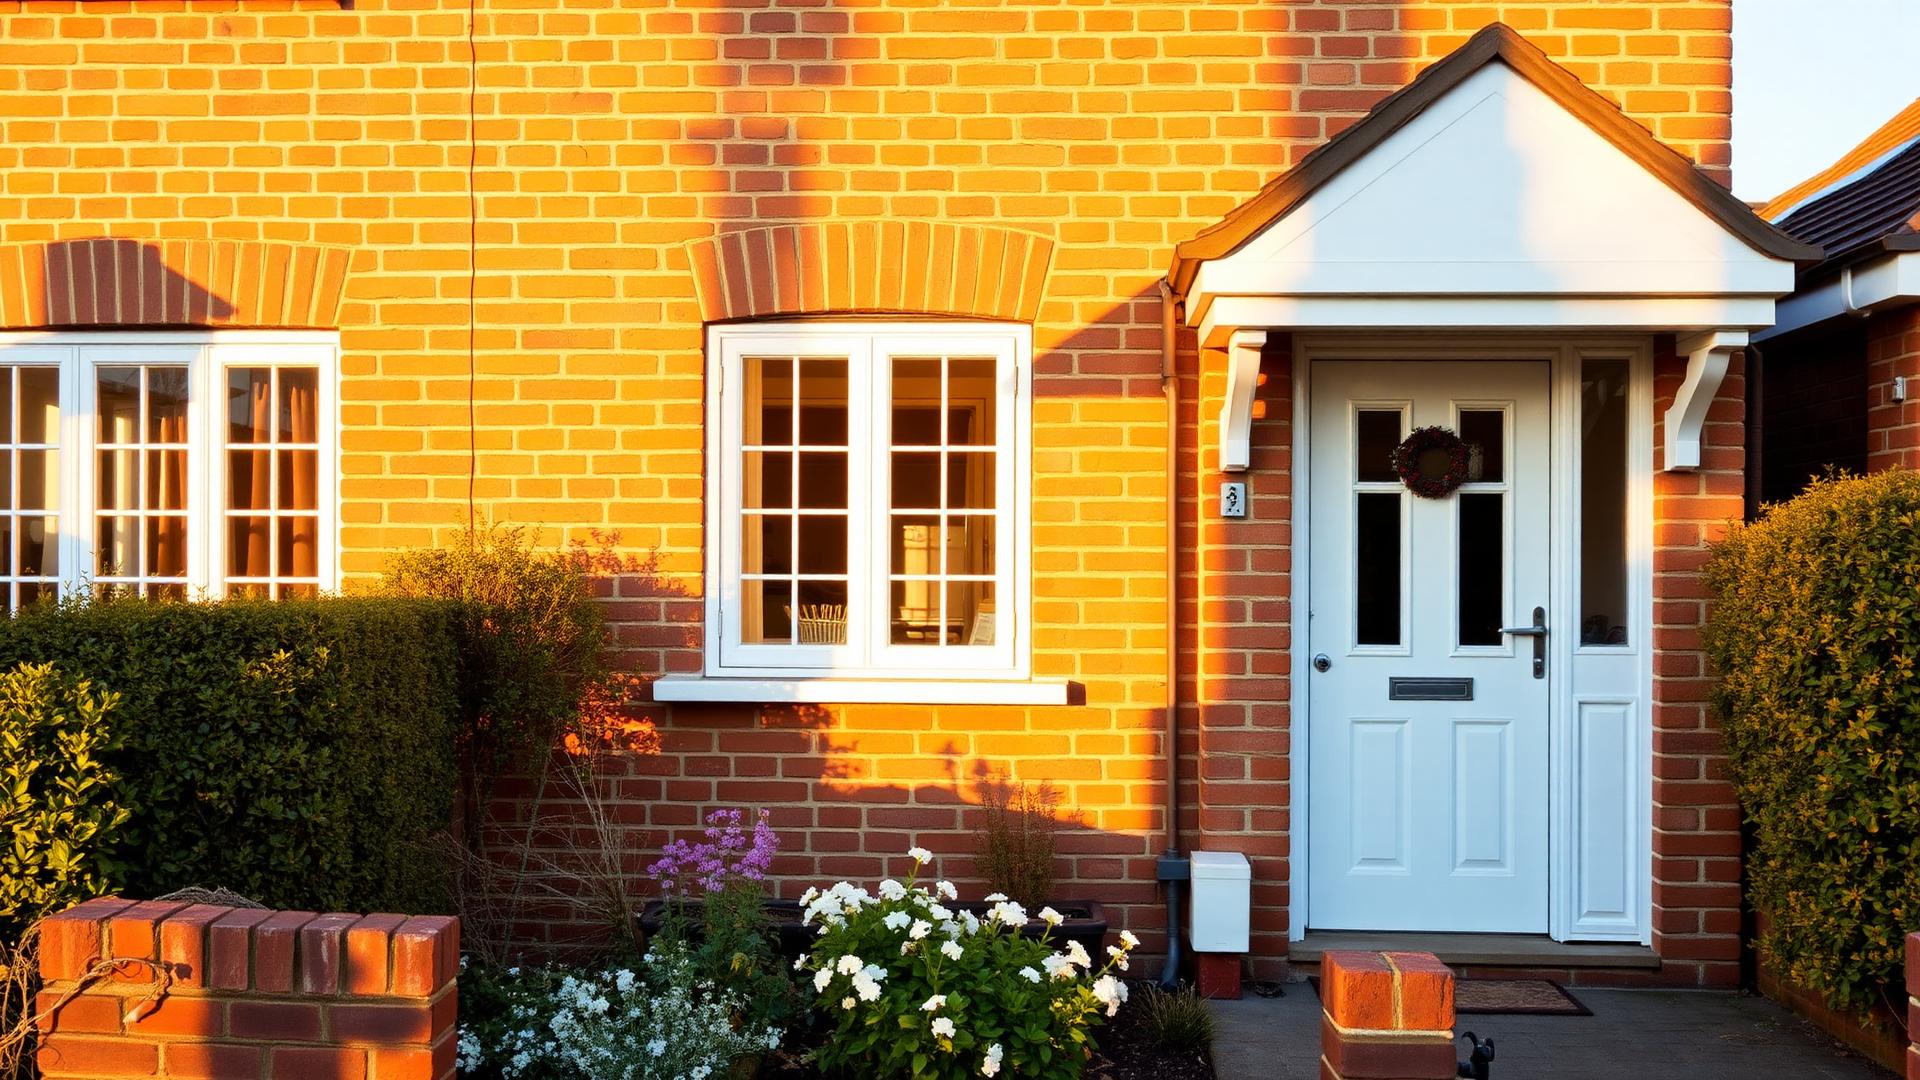
A classic UK brick council home with a white front door in golden light

What Is Right to Buy?

Right to Buy allows qualifying council tenants in England to purchase their home at a discount from its market value. Eligibility and discount rules are determined by the scheme and administered by your landlord β€” not every council tenant qualifies.

Current GOV.UK guidance states that eligibility includes factors such as the property being your only or main home, the property being self-contained, secure tenancy status and qualifying public sector tenancy history.

This guide focuses on Right to Buy in England. Different rules apply in Scotland, Wales and Northern Ireland β€” please check the guidance for the nation where you live.

Who Might Qualify?

Eligibility depends on the current scheme rules. Factors that are commonly considered include:

  • Secure tenancy status
  • Public sector tenancy history
  • The property is your only or main home
  • The property is eligible and self-contained
  • Joint applications may be possible
  • Preserved Right to Buy where the property transferred landlord

Qualifying tenancy periods and other rules change over time, so we do not quote fixed figures here. The official guidance always holds the current position.

Preserved Right to Buy

Some tenants whose council property transferred to another landlord, such as a housing association, might retain a Preserved Right to Buy.

If your home was transferred, confirm your position directly with your landlord before making any decisions.

Right to Acquire

Right to Buy and Right to Acquire are different schemes. Some housing association tenants who do not qualify for Right to Buy might qualify for Right to Acquire.

The schemes are not interchangeable β€” check your eligibility directly with your landlord and the current government guidance.

How Does the Discount Work?

The Right to Buy discount depends on factors including:

  • Property type
  • Property value
  • Location
  • Length of qualifying tenancy
  • Previous use of Right to Buy
  • Relevant landlord expenditure

Government rules and discount limits change, so we do not quote fixed maximum values. Current guidance also explains circumstances where some discount might need to be repaid after an early sale.

Can the Discount Help with the Deposit?

Some mortgage lenders might treat some or all of the Right to Buy discount as part of the equity in the property when assessing the mortgage. Lender criteria differ, and some circumstances might still require the buyer to provide their own funds.

Whether a lender will consider the discount in place of a cash deposit depends on that lender's verified criteria β€” this is something we check for you as part of a regulated advice process, rather than something that can be guaranteed in advance.

What Will a Mortgage Broker Need?

Having your documents ready helps your broker assess affordability and identify suitable lenders. Exact requirements vary, but you should expect to provide some or all of the following.

  • Valid passport
  • Driving licence where applicable

Understanding the Section 125 Offer Notice

If your application is accepted, your landlord will send you formal documentation β€” commonly known as the Section 125 Offer Notice β€” setting out the details of the proposed purchase, including the property's market value, your discount, the price you would pay and a description of the property.

You and your solicitor should review this document carefully before deciding to proceed. We do not provide legal advice β€” your solicitor will advise you on the legal content of the offer.

From Tenant to Homeowner

Becoming the owner introduces additional financial responsibilities that your landlord currently handles. Costs to budget for include:

Mortgage payments

Buildings insurance

Repairs

Maintenance

Service charges for some properties

Major works charges for some leasehold properties

Legal costs

Mortgage fees

Other property related costs

Buying a Leasehold Flat?

Buyers of flats should review service charges and information concerning planned major works carefully. Major works to the building can result in significant charges to leaseholders, so understand what is planned before you commit.

Credit History

Lenders review credit history as part of the mortgage application. Issues they may consider include:

  • Missed payments
  • Defaults
  • CCJs
  • Credit card balances
  • Loans
  • Car finance
  • Other financial commitments

Lender criteria differ, and previous credit issues do not automatically mean a decline β€” but approval is never guaranteed. A broker can identify lenders whose criteria may suit your circumstances.

The Right to Buy Process

  1. 1

    Check your potential eligibility

  2. 2

    Apply to your landlord

  3. 3

    Landlord confirms eligibility

  4. 4

    Property is valued

  5. 5

    Receive formal offer documentation

  6. 6

    Review purchase price and discount

  7. 7

    Review mortgage affordability

  8. 8

    Select a mortgage following appropriate advice

  9. 9

    Submit the mortgage application

  10. 10

    Mortgage valuation and underwriting

  11. 11

    Solicitor completes legal work

  12. 12

    Exchange where applicable

  13. 13

    Completion

  14. 14

    Become responsible for the property as the homeowner

Important Questions Before Buying

  • Can I comfortably afford the mortgage?
  • What happens if interest rates change?
  • What service charges apply?
  • Are major works planned?
  • What repairs will become my responsibility?
  • How long do I plan to remain in the property?
  • Would I need to repay any discount if I sold?
  • What other costs will I have as a homeowner?

Right to Buy FAQs

Right to Buy is a government scheme that allows qualifying council tenants in England to purchase their home at a discount from its market value. Eligibility and discount rules are set by the scheme and administered by the landlord.

Considering Buying the Home You Already Live In?

Before committing to a Right to Buy purchase, understand your mortgage affordability, the property costs and the financial responsibilities you will take on as the homeowner.

Your home may be repossessed if you do not keep up repayments on your mortgage. Eligibility for Right to Buy does not guarantee mortgage approval β€” all mortgage applications are subject to lender criteria and affordability assessment.